From 1 January 2027, certain individuals leaving Italy, including non-domiciled residents (“non-doms”), could become subject to a new exit tax on unrealised gains arising from qualifying financial assets. The proposal has recently been introduced as part of Italy’s draft 2027 Budget and remains subject to parliamentary approval.
In brief, the proposed measure would apply to individuals transferring their tax residence outside Italy after having been Italian tax residents for at least six of the preceding ten tax years, provided they hold qualifying financial assets or rights with an aggregate value of at least €800,000.
Affected individuals, particularly foreign nationals who relocated to Italy to benefit from its non-dom tax regime, may wish to proactively review their relocation options and consider alternative jurisdictions that better accommodate their business, family and personal tax needs.
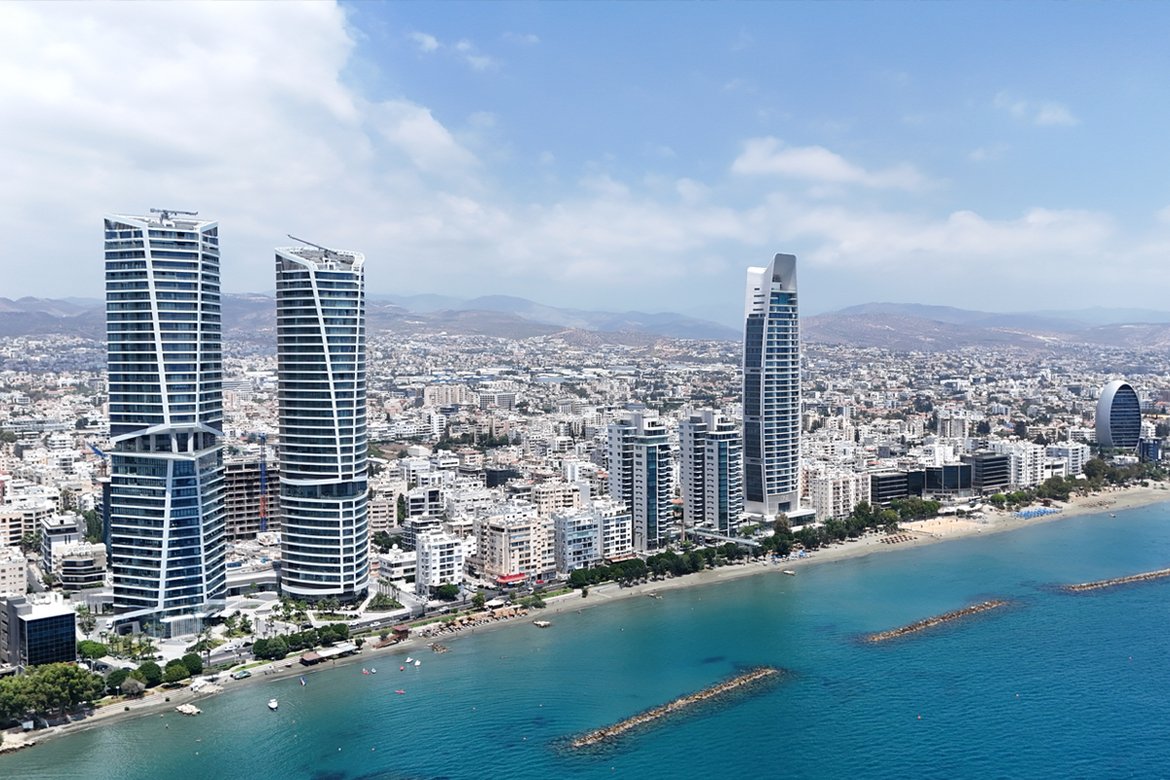
One jurisdiction that certainly deserves serious consideration is Cyprus!
Cyprus offers one of Europe's most competitive and practical non-dom tax regimes. Foreign individuals can benefit from this regime simply by becoming Cyprus tax residents. Cyprus tax residence can generally be established either under the standard 183-days rule or through the alternative 60-days route, subject to easy to meet conditions. The 60-days route provides considerable flexibility, particularly for internationally mobile individuals who do not wish to spend more than half of each year in any one country. Click here for further details.
The uniqueness of the Cyprus non-dom regime is that it out-rightly tax exempts passive nature incomes like dividends, interest, gain from sale of shares and capital gains of real estate situated outside Cyprus. These benefits are particularly relevant to high-net-worth individuals whose wealth and income are primarily derived from such sources.
These exemptions are available irrespective of the country from which the income is sourced and irrespective of whether the income is subsequently remitted and used in Cyprus. Furthermore, the Cyprus non-dom regime does not entail any element of lump-sum tax payment nor any needed investment.
Beyond its non-dom regime, Cyprus offers a range of other favourable personal tax provisions, as well as a highly competitive corporate tax framework, making it an attractive jurisdiction for both personal and corporate relocation.
Cyprus is more than just a tax destination as it offers a well-established international business environment and an all-round ecosystem that can accommodate all needed qualitative elements. Last but not least, Cyprus is expected to join the Schengen Area in late 2027, further enhancing its international appeal.
How can Totalserve assist?
Totalserve can provide comprehensive assistance to individuals and businesses considering a relocation to Cyprus. Should you be interested for more information or assistance may contact us at [email protected]